GST Refund Process: RFD-01 to Appeal — Timelines, Deficiency Memos & 57th Council Changes
GST refund process step by step: RFD-01, deficiency memo, 60-day order, interest, appeal and GSTAT, with the 57th GST Council recommendations on automation.
Filing an RFD-01 is the easy part. The real work begins when the portal returns a deficiency memo, when a show cause notice arrives for a refund you were sure was in order, or when 60 days pass in silence. This final part of the series follows a claim from filing to appeal, with the timelines that apply today and the changes the 57th GST Council has recommended.
The refund lifecycle step by step
| Step | Form | Timeline | Provision |
|---|---|---|---|
| 1. Application | RFD-01 | Within two years from the relevant date | s.54(1) |
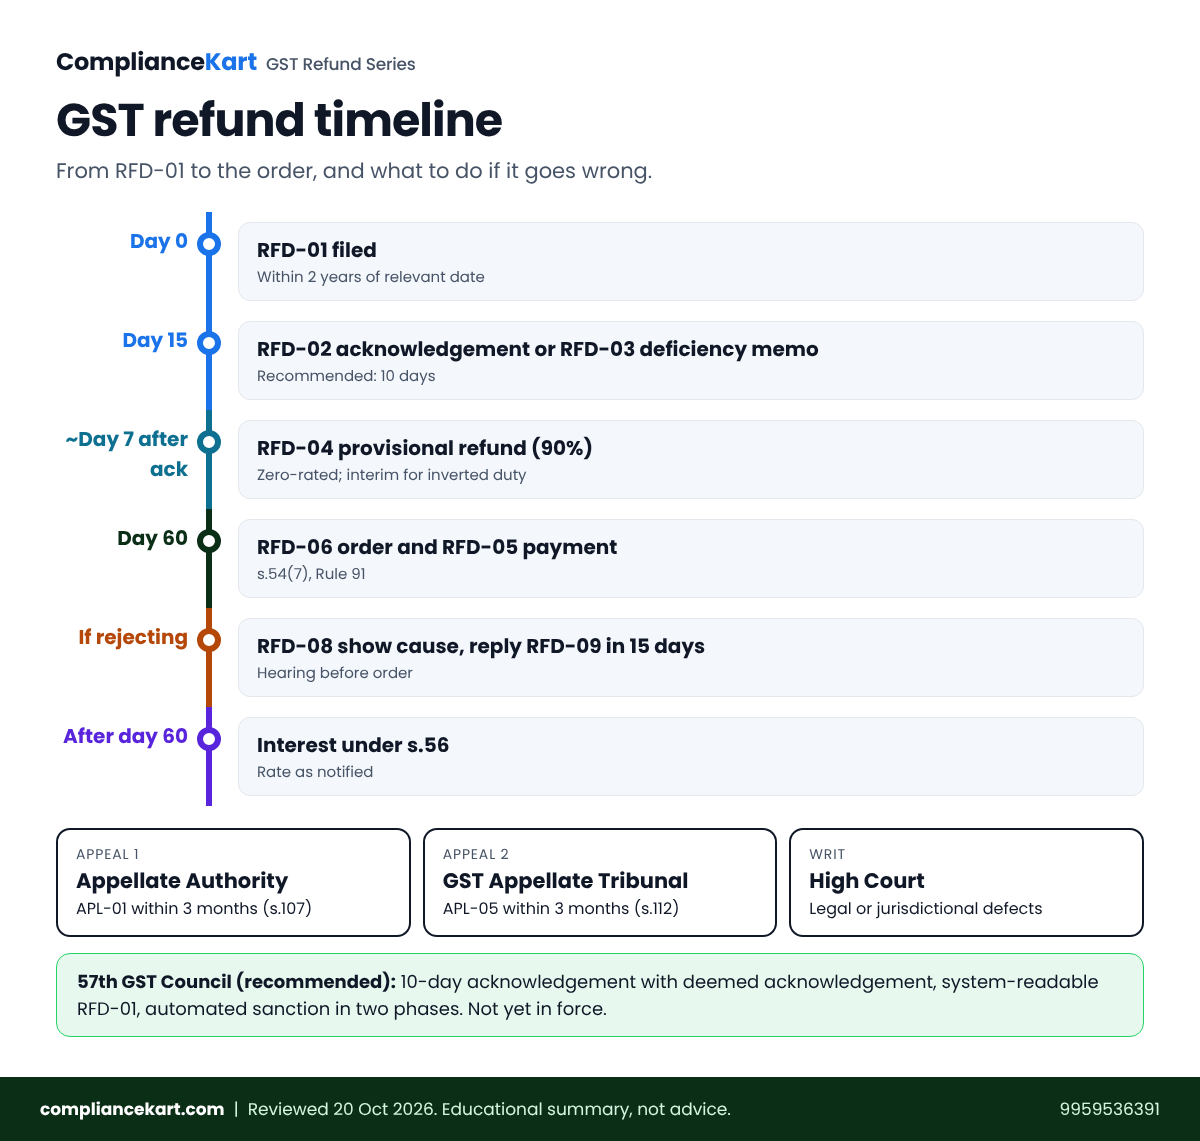
| 2. Acknowledgement or deficiency memo | RFD-02 / RFD-03 | 15 days from filing (recommended: 10 days) | Rule 90(2), (3) |
| 3. Provisional refund (zero-rated; interim for inverted duty) | RFD-04 | 90%; paid after acknowledgement, within about 7 days verify | s.54(6); Rule 91(2) |
| 4. Final sanction and payment | RFD-06 / RFD-05 | 60 days from a complete application | s.54(7); Rule 91(1) |
| 5. Show cause notice if refund is to be rejected | RFD-08 / reply RFD-09 | Reply within 15 days; hearing before order verify | Rule 92(3) |
| 6. Withholding or set-off against dues | RFD-07 | Where returns or dues are pending | s.54(10); Rule 93 |
| 7. Interest on delay | — | After 60 days from the application | s.56 |
Deficiency memos and show cause notices
A deficiency memo (RFD-03) is not an order. It lists defects in the application and requires a fresh application after correction. Because it is not an order, it is not appealable, and the practical remedies are to correct and re-file, or, where the memo is legally unsustainable, to approach the High Court. Courts have quashed memos that rejected claims on a legally incorrect reading of the Rules, and directed reprocessing; an example is the Gujarat High Court in Pranav Overseas LLP v. Union of India (2 July 2026), concerning Rule 89(5) verify. The two-year limit keeps running while this happens, so file the corrected application early.
A show cause notice (RFD-08) is different: it is a statutory step before an adverse order. Reply (RFD-09) within the prescribed period, address each stated ground with documents, and ask for a personal hearing. A reply that merely repeats the claim rarely works.
| Common ground in RFD-03 / RFD-08 | Response approach |
|---|---|
| Mismatch between GSTR-1, GSTR-3B and refund statements | Provide a reconciliation, with explanations for timing differences |
| Invalid or unmatched shipping bill / EGM (exports) | Match with ICEGATE data; rectify shipping bill details where possible |
| FIRC / e-BRC not produced (services) | Produce bank realisation proofs; explain timing |
| ITC not in GSTR-2B / supplier default | Demonstrate payment and supply; evaluate Section 16(2) risk |
| Input services included in an inverted-duty claim | Segregate; claim on the legally permitted base; see Part 3 |
| Refund claimed beyond two years | Check the relevant date under Explanation (2); verify any excluded period verify |
Interest on delayed refunds
If the refund due under Section 54(5) is not paid within 60 days of receipt of the application, interest runs from the expiry of that period under Section 56. The rate is notified (6% a year for the standard case, and a higher rate where the refund follows an appellate or court order) verify. Where the delay arises from an order passed on appeal or by a court, interest runs on the refund pursuant to that order. Interest on a refunded pre-deposit follows Section 115 (Part 4). Note that for the period during which a refund is withheld under Section 54(11) on the ground of fraud, the interest is limited to the rate fixed by Section 54(12).
If the claim is rejected
| Forum | Time limit | Notes |
|---|---|---|
| Appellate Authority (Section 107), FORM GST APL-01 | 3 months from communication; the authority may condone a further 1 month | Whether a pre-deposit is payable on appeal against a refund rejection is not uniformly applied in practice; confirm before filing verify |
| GST Appellate Tribunal (Section 112), FORM GST APL-05 | 3 months from communication of the appellate order, condonable by up to 3 months | The Tribunal is the last fact-finding forum; build the record at the first appeal |
| High Court (Article 226) | No fixed period, but delay is fatal in practice | For jurisdictional, vires or natural-justice issues, and for quashing unsustainable deficiency memos |
Our guides on first appeal vs GSTAT appeal, grounds that win a GST appeal and GSTAT filing deadlines cover the appellate stages.
Primary position: appeal on the legal ground (formula, relevant date, definition) where the facts are clean. Alternative: re-file a corrected claim if the rejection is purely documentary and time remains. Risk: low where the defect is documentary and curable; moderate to high where the dispute is about the legal scope of the refund (input services, retrospectivity, nil-rated outputs). Practical step: never let the two-year clock lapse while waiting on a department response.
Pre-filing checklist
- Identify the correct refund route and the relevant date, and diarise the last date.
- Reconcile GSTR-1, GSTR-3B and GSTR-2B for every period in the claim.
- Prepare the statement and annexures required for the route, and keep supporting invoices indexed.
- Settle pending returns and dues, because Section 54(10) lets the department withhold or set off.
- Prepare the unjust-enrichment declaration or CA/CMA certificate where Rule 89(2) requires it.
- File the application, download the acknowledgement and calendar day 60 for interest.
How the 57th GST Council recommendations change the process
- Acknowledgement or deficiency memo in 10 days (from 15), with deemed acknowledgement if none is issued.
- Phase 1: automatic sanction of excess cash ledger refunds; 90% provisional sanction for zero-rated and inverted-duty claims based on system risk evaluation.
- Phase 2: system acknowledgement after verification; automated full sanction of zero-rated claims after adjusting pending dues.
- RFD-01 in a system-readable format, with no scanned documents for zero-rated and inverted-duty claims.
- Clarificatory circulars on issues causing differing field interpretations (the issues are not specified in the available reports).
For taxpayers the implication is that data quality will matter more than documents: the system will read RFD-01 fields and match them with returns. A claim that is reconciled before filing is also the claim most likely to pass an automated risk filter. Until amendments, rules and portal changes are notified, the process in the table above governs. Track the status in our note on the 57th Council refund recommendations.
Hyderabad context
Businesses in Hitech City, Kondapur, Gachibowli, Kokapet and the Financial District file with the jurisdictional Central or State authority shown on their registration, and the appeal lies to the Appellate Authority for that office. Because refund claims by exporters and pharma units are subject to heavy statement scrutiny, many claims are decided at the deficiency-memo stage; early reconciliation avoids most of these.
Why work with ComplianceKart
A refund that comes back as a rejection needs a different skill from a refund that goes through. ComplianceKart is a boutique practice bringing CAs, CSs and advocates under one roof, much like a multi-speciality hospital that has the physician, the surgeon and the rehabilitation team coordinating on one patient. We prepare the claim, reply to the notice, and represent the matter on appeal, so the argument you make in a reply is the one that survives later. We cannot guarantee the outcome or the time taken.
Frequently asked questions
How long does a GST refund take?
The proper officer must pass the order within 60 days of a complete application under Section 54(7). Provisional refund of 90% can be sanctioned earlier for zero-rated claims. Interest under Section 56 is payable on delay beyond 60 days. The 57th GST Council has recommended further automation, not yet in force.
What is a deficiency memo in GST refund?
It is Form GST RFD-03, issued within 15 days of filing, listing defects in the application. It is not an order; you must file a fresh application after correcting the defects, and the two-year limit continues to run.
What is the difference between RFD-03 and RFD-08?
RFD-03 is a deficiency memo issued at the acknowledgement stage. RFD-08 is a show cause notice issued before rejecting a claim in whole or part, to which you reply in RFD-09 and are heard before the final order.
Can I appeal if my GST refund is rejected?
Yes. A rejection order can be appealed to the Appellate Authority in FORM GST APL-01 within three months under Section 107, and then to the GST Appellate Tribunal under Section 112. A High Court writ is available for jurisdictional or legal defects.
How will the 57th GST Council recommendations change refunds?
They recommend a 10-day acknowledgement window, automatic refund of excess cash ledger balance, 90% system-based provisional sanction for zero-rated and inverted-duty claims, system-readable RFD-01 and fuller automation in Phase 2. They need legal amendments and notifications before they apply.
What interest do I get on a delayed GST refund?
Interest under Section 56 for delay beyond 60 days from the application, at the notified rate, and under Section 115 for refund of pre-deposit. Check the current notification for the rate before computing.
Refund rejected or stuck?
Share the notice or memo and the period. We will review the grounds, the time left and the options.
WhatsApp usEmailCall 9959536391GST notice & litigation supportContinue the series
Disclaimer. This article is for general information on Indian GST law as at 20 October 2026 and is not advice on any specific case. Refund eligibility depends on facts, period and documents. Items marked verify should be checked against the current official text before reliance. Contact: team@compliancekart.com · 9959536391 · compliancekart.com.
Need this done for your business?
Send us one message. A CA, CS or Advocate replies within a working day — no forms, no obligation.