Types of GST Refund in India: 14 Ways to Claim Your Money Back (Startups, Pharma & IT)
Types of GST refund explained: 14 routes under Section 54, who can claim, time limits and forms. A guide for startups, pharma and IT exporters in Hyderabad.
A SaaS founder in Kondapur exports software services, pays 18% GST on rent, cloud and consultants, and watches an unused credit balance grow every month. A formulations unit near Jeedimetla buys active ingredients taxed at 18% and sells medicines taxed at 5%. A Gachibowli startup deposits ₹3 lakh in the cash ledger, then finds it paid the wrong head. All three have money with the Government. None of them claims it the same way.
What Section 54 actually says
Section 54 is the gateway for almost every refund. It lets any person claim a refund of tax, interest or any other amount paid, within two years from the relevant date, in the prescribed form and manner. The mechanics below apply across routes, with route-specific rules layered on top.
| Feature | Position | Provision |
|---|---|---|
| Time limit | Two years from the relevant date | s.54(1) |
| Form | FORM GST RFD-01 on the GST portal (special claimants use a separate form) | s.54(1); Rule 89 |
| Refund of unutilised ITC | Allowed only for (i) zero-rated supplies made without payment of tax, and (ii) inverted duty structure, subject to the statutory exclusions | s.54(3) |
| Order timeline | Within 60 days of receiving a complete application | s.54(7) |
| Provisional refund | 90% for zero-rated supplies (prescribed conditions) | s.54(6); Rule 91 |
| Unjust enrichment | Refund goes to the Consumer Welfare Fund unless the burden was not passed on or the claim falls in the listed exceptions | s.54(4), (5), (8); s.57 |
| Minimum amount | No refund below ₹1,000 | s.54(14) |
| Interest | Payable if refund is delayed beyond 60 days from the application | s.56 |
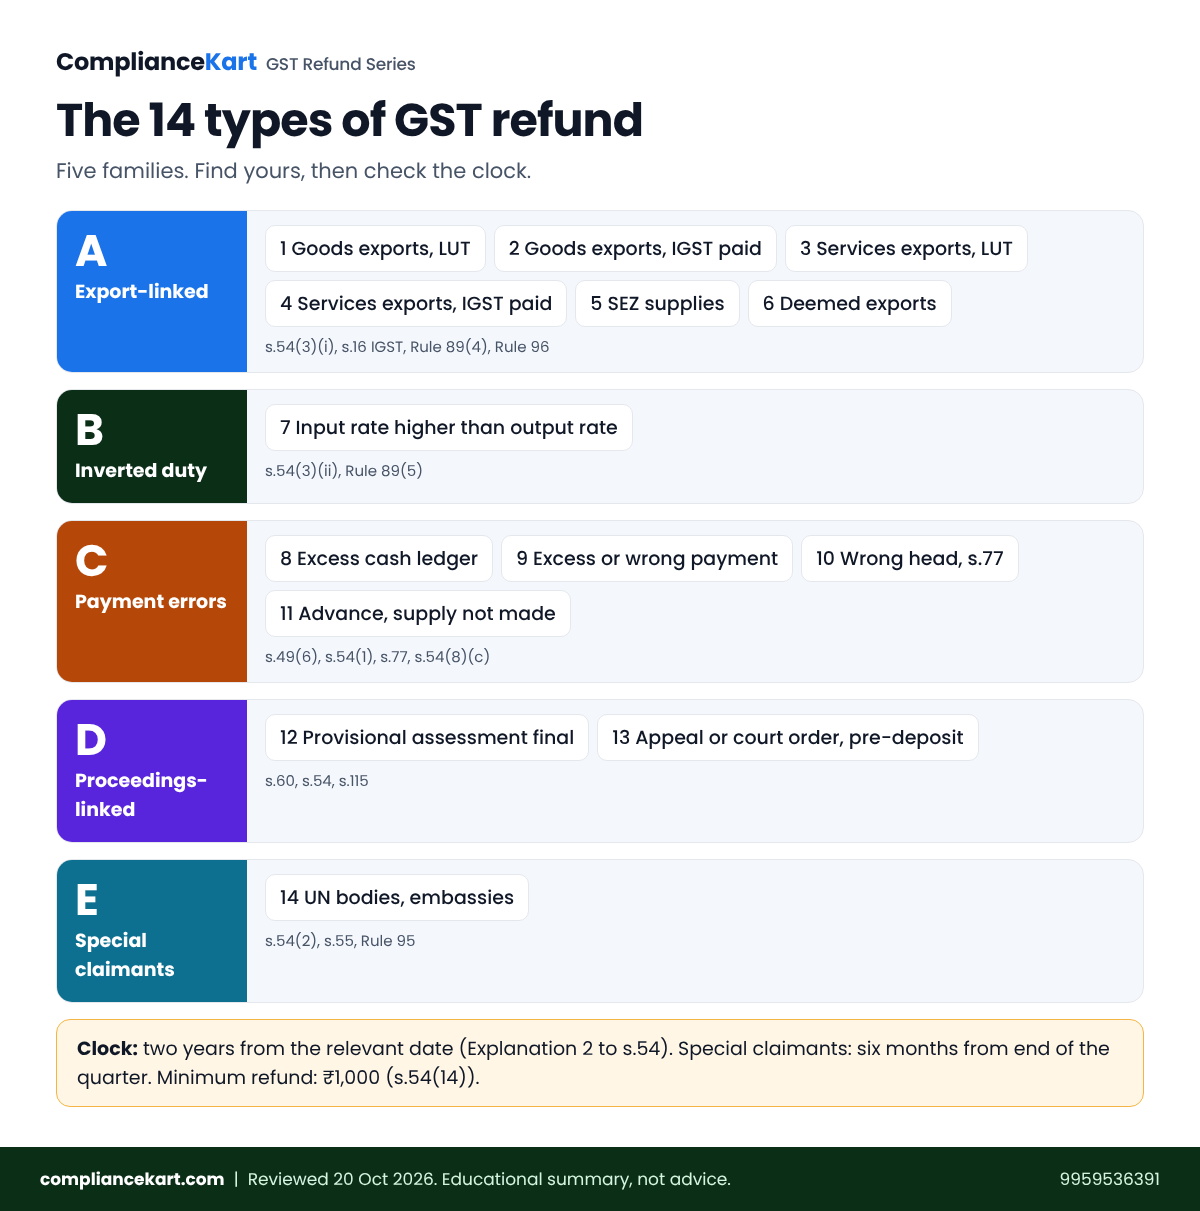
The 14 routes, family by family
| # | Refund route | Who typically claims | Governing provision | Clock starts (relevant date) |
|---|---|---|---|---|
| 1 | Export of goods without payment of tax (LUT) — refund of unutilised ITC | Goods exporters | s.54(3)(i) CGST; s.16 IGST; Rule 89(4) | Ship/aircraft leaves India, goods cross frontier, or post dispatched — Expl. (2)(a) |
| 2 | Export of goods with payment of IGST | Goods exporters | s.16(3)(b) IGST; s.54(1); Rule 96 | Same as above |
| 3 | Export of services without payment of tax (LUT) — unutilised ITC | IT, SaaS, consulting, GCC units | s.54(3)(i); s.2(6) & s.16 IGST; Rule 89(4) | Expl. (2)(c): foreign-currency receipt or invoice date, as applicable |
| 4 | Export of services with payment of IGST | Exporters who pay and claim | s.16(3)(b) IGST; s.54(1); Rule 89 | Expl. (2)(c) |
| 5 | Supplies to SEZ unit / developer (with or without payment) | Suppliers to SEZs | s.16 IGST; s.54 | Explanation (2) to s.54 verify |
| 6 | Deemed exports | Supplier or recipient, as the rules permit | s.147; s.54; Rule 89 | Expl. (2)(b): date of return for those supplies |
| 7 | Inverted duty structure | Pharma, textiles, EV and other inputs taxed higher than outputs | s.54(3)(ii); Rule 89(5) | Expl. (2)(e): end of the financial year in which the claim arises |
| 8 | Excess balance in electronic cash ledger | Anyone who over-deposited cash | s.49(6); s.54(1) | Date of deposit/payment verify |
| 9 | Excess or erroneous payment of tax | Anyone who paid more than due | s.54(1) | Expl. (2)(h): date of payment of tax |
| 10 | Intra-State supply held inter-State (or the reverse) | Wrong CGST+SGST vs IGST | s.77 CGST; s.19 IGST | Count conservatively from the original payment verify |
| 11 | Advance received but supply not made (refund voucher issued) | Startups with cancelled orders | s.54(8)(c); s.31(3)(e); Rule 51 | Expl. (2)(h) |
| 12 | Finalisation of provisional assessment | Persons under s.60 provisional assessment | s.60; s.54 | Expl. (2)(f): date of adjustment after final assessment |
| 13 | Order of appellate authority, Tribunal or court — including pre-deposit | Appellants | s.54(1); s.115; Rules 89, 94 | Expl. (2)(d): date the judgment/order is communicated |
| 14 | Special claimants: UN bodies, embassies, notified persons | Eligible entities | s.54(2); s.55; Rule 95 | Six months from end of the quarter of receipt of supply |
Relevant-date clauses are from Explanation (2) to Section 54. Items marked verify need a check against the latest Circular or the Act text before you file.
Family A: export-linked refunds (routes 1 to 6)
Exports and supplies to SEZs are “zero-rated” under Section 16 of the IGST Act. A supplier chooses between supplying under a Letter of Undertaking (LUT) and claiming accumulated ITC, or paying IGST and claiming it back. Part 2 of this series walks through that choice and the formulas.
Family B: inverted duty (route 7)
If you pay a higher rate on inputs than you charge on outputs, the credit piles up. Section 54(3)(ii) allows a refund of that accumulation, but only for inputs, only for taxable outputs, and only within the Rule 89(5) formula. Part 3 covers it, including the pharma position after the 22 September 2025 rate changes.
Family C: payment-error refunds (routes 8 to 11)
Over-deposits, wrong-head payments and cancelled advances. These are cash refunds of tax actually paid, so the proof is in the ledgers and the returns. Part 4 covers them along with pre-deposit refunds.
Family D: proceedings-linked refunds (routes 12 and 13)
These arise after an assessment is finalised, or after an appellate authority, the Tribunal or a court orders a refund. Interest on a refunded pre-deposit runs under Section 115. Part 5 covers procedure, rejection and appeal.
Family E: special claimants (route 14)
United Nations bodies, consulates and embassies, and other notified persons can claim tax paid on inward supplies under Section 54(2) read with Section 55, within six months from the end of the quarter in which the supply was received.
Which route fits startups, pharma and IT
| Business | Most common routes | What usually goes wrong |
|---|---|---|
| Startups (early-stage, high input costs) | 3, 4, 8, 9, 11 | Input credit accumulates; cash deposited in error; advances refunded to customers without a refund voucher |
| IT, SaaS and GCC units exporting services | 3, 4 (and 7 only if outputs are domestic and inverted) | Supply does not meet the export-of-services definition; foreign-currency receipt not matched; LUT lapsed after 31 March |
| Pharma manufacturers and exporters | 1, 2, 7 | Nil-rated or exempt outputs excluded from the inverted-duty claim; input services included in a claim that covers inputs only; mismatch between returns and refund statements |
| Pharma and device distributors | 7 (limited), 8, 9 | Assuming every accumulated credit is refundable. It is not. |
Unutilised ITC is refundable only under Section 54(3), that is, for zero-rated supplies without payment of tax and for inverted duty. A balance that simply builds up because you buy more than you sell is not a refund route. Credit on capital goods is outside the inverted-duty refund as the statute stands. The 57th GST Council has recommended a change for input services and capital goods (see the table above); it needs amendments and is not law yet verify. Our detailed note on the 57th Council refund recommendations tracks it.
What the 57th GST Council changes for refunds
The 57th GST Council (8 October 2026) recommended a two-phase, system-driven refund process. Nothing below is in force yet. Where the recommendation touches a route, we flag it in the relevant part of this series.
| Area | Today (current law) | Recommended by the 57th Council |
|---|---|---|
| Acknowledgement / deficiency memo | 15 days (Rule 90) | 10 days; application deemed acknowledged if none issued |
| Zero-rated and inverted-duty claims | 90% provisional for zero-rated (s.54(6)); inverted duty on interim basis per Instruction 06/2025-GST verify | 90% provisional sanction by the system on risk evaluation, for both |
| Excess cash ledger balance | Claim through the portal | Phase 1: full refund sanctioned automatically |
| Documents with RFD-01 | Scanned uploads | System-readable RFD-01; no scanned uploads for zero-rated and inverted-duty claims |
| Rule 89(4) 1.5x like-goods cap on goods turnover | In the Rules | Proposed to be removed |
| Section 54(14) ₹1,000 floor | Applied per tax head verify | Applied on total of CGST, SGST/UTGST and IGST |
| Inverted duty: input services | Not refundable; s.54(3)(ii) speaks of inputs | Refundable for ITC availed on or after 1 Nov 2026 |
| Inverted duty and zero-rated: capital goods | Not refundable | Refundable, spread over 60 months, for ITC availed on or after 1 Apr 2027 |
| Interest on refund of pre-deposit | s.115 | s.115 to become a standalone provision; clarifying circular |
The Finance Act, 2026 had already moved in the same direction: it extends the 90% provisional refund to inverted-duty claims and removes the ₹1,000 floor for IGST refunds on exports of goods, both from dates to be notified verify. CBIC Instruction No. 06/2025-GST (3 October 2025) allows risk-based provisional sanction in the meantime verify. Do not plan cash flow on any of these until the notification or circular is in hand.
Hyderabad context
Exporters of services around Hitech City, Kondapur, Gachibowli and the Financial District usually sit in routes 3 and 4. Formulation and bulk-drug units in the Jeedimetla, Patancheru and Genome Valley belts mostly sit in routes 1, 2 and 7. The jurisdictional GST officer for your registration decides the claim, so file with the state-or-centre authority shown on your registration. If you are a Telangana-based startup, route 8 and 9 mistakes are typically introduced during the first year of GST filing.
Why work with ComplianceKart
Refund work crosses disciplines. Eligibility is a GST question, export proceeds are a FEMA question, the books must tie to the returns, and a rejection has to be argued in an appeal. ComplianceKart is a boutique practice bringing Chartered Accountants, Company Secretaries and advocates under one roof, much like a multi-speciality hospital where the diagnosis, the procedure and the follow-up are coordinated rather than handed from clinic to clinic. For a refund that means one team checking route, working, evidence and appeal strategy together. We cannot promise any refund or its timing; each claim is decided by the department on its facts.
Frequently asked questions
How many types of GST refund are there?
The law does not number them. In practice there are 14 routes: six export-linked, one for inverted duty, four for payment errors, two arising from proceedings and one for special claimants. All sit under Section 54 of the CGST Act, 2017, read with Section 55 for special claimants.
What is the time limit to claim a GST refund?
Generally two years from the relevant date under Explanation (2) to Section 54. The relevant date differs by route, for example the date the goods leave India for exports, or the end of the financial year for inverted duty. Special claimants have six months from the end of the quarter.
Which form is used to claim a GST refund?
FORM GST RFD-01 on the GST portal for most claims. Special claimants such as embassies and UN bodies use a separate prescribed form. The order and payment are recorded in the RFD-06 and RFD-05 forms.
Can I get a refund of all accumulated input tax credit?
No. Section 54(3) allows a refund of unutilised ITC only for zero-rated supplies without payment of tax and for inverted duty structure. Other credit balances are carried forward and used against future tax liability.
Is there a minimum amount for a GST refund?
Yes. Section 54(14) provides that no refund is paid if the amount is below ₹1,000. The Finance Act, 2026 provides an exception for IGST refunds on exports of goods, from a date to be notified.
Do I get interest if the GST refund is delayed?
Interest is payable under Section 56 if the refund is not paid within 60 days of the application. Interest on a refunded pre-deposit runs under Section 115. The rates are set by notification; check the current notification before computing.
Not sure which refund route applies to you?
Tell us your business type, the ledger balance and the period. We will tell you which route fits and what evidence is needed.
WhatsApp usEmailCall 9959536391GST registration & filingContinue the series
Disclaimer. This article is for general information on Indian GST law as at 20 October 2026 and is not advice on any specific case. Refund eligibility depends on facts, period and documents. Items marked verify should be checked against the current official text before reliance. Contact: team@compliancekart.com · 9959536391 · compliancekart.com.
Need this done for your business?
Send us one message. A CA, CS or Advocate replies within a working day — no forms, no obligation.