ESOP in India: The Complete Guide for Founders and Employees (2026)
A story-style, plain-English guide to ESOPs in India: how they work, who can get them, vesting, valuation, tax, FEMA, mistakes and checklists for founders and employees.
How to read this guide: it is one story, told in chapters. Follow Priya, a first employee, and by the last page you will understand ESOPs better than most people who hold one. Names and numbers in the story are fictional examples, not real clients.
Jump to: What is an ESOP · Who can get one · Setting it up · Pool size · Vesting · Valuation · Tax · FEMA · ESOP vs RSU · Mistakes · Checklists · FAQs
Prologue: the Friday offer
Friday evening, Kondapur. Ananya and Vikram, co-founders of Zephyr Works (a fictional logistics-software startup), are staring at a resignation email that has not been sent yet.
Priya, their first engineer, has a job offer from a big tech company in Gachibowli. Salary: 40% higher. Zephyr cannot match it. Cash is tight.
Ananya says what founders everywhere say: “We can’t pay you more. But we can make you an owner.”
Priya raises an eyebrow. “A promise on paper. What is it actually worth?”
That is the right question. Answering it takes the rest of this guide. Let’s begin where Priya did: with the basics.
Chapter 1: What exactly is an ESOP?
Think of a discount coupon for shares. It says: “After you have stayed long enough, you may buy shares at today’s price, even if they cost much more by then.” You are not forced to buy. And until you do, you are not a shareholder: no vote, no dividend.
The Companies Act, 2013 (Section 2(37)) defines it the same way: a right given to employees to buy or subscribe to shares at a future date at a pre-determined price.
| Word you will hear | Plain meaning | Priya’s example |
|---|---|---|
| Grant | The day the company gives you the options | 1 April 2026: 4,800 options |
| Vesting | Earning the right to use them, over time | 25% after year 1, the rest monthly |
| Cliff | A waiting period; nothing vests before it | 12 months |
| Exercise price (strike) | What you pay per share | ₹20 |
| Exercise | Using the coupon: pay and receive shares | She buys 1,000 shares for ₹20,000 |
| Fair market value (FMV) | What the share is truly worth that day | ₹220 on exercise day |
| Pool | Shares reserved for all employees | 10% of the company |
| Leaver | Someone who quits or is let go | Matters for what you keep |
Priya’s coupon is not cash. But it is not nothing either. If Zephyr grows, the gap between ₹20 and the share’s real value becomes her wealth. Her next question: “Fine. But how does this actually work, start to finish?”
Chapter 2: The five stops of an ESOP
Every ESOP, in every company, travels the same road. Learn these five stops and nothing about ESOPs will confuse you again.
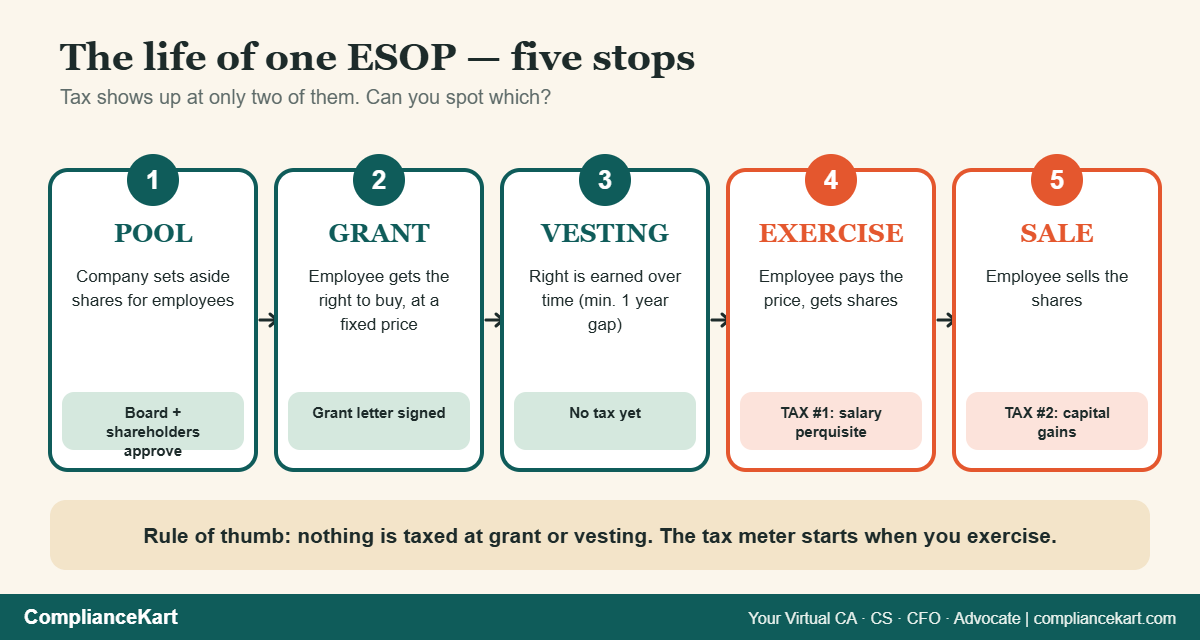
- Pool: founders and shareholders approve a block of shares for employees.
- Grant: each employee gets a letter: how many options, at what price.
- Vesting: the employee earns the options over time. The law requires at least one year between grant and the first vesting.
- Exercise: the employee pays the price and the company allots shares.
- Sale: the employee sells, to an investor, an acquirer, the public market or the company itself.
Notice what is missing: no tax at stops 1 to 3. The taxman arrives at stop 4. We will meet him properly in Chapter 8. First, a question Ananya asked her lawyer: “Who is even allowed to receive these?”
Chapter 3: Who can get an ESOP, and who cannot
Under Rule 12 of the Share Capital Rules, an unlisted company can grant options only to certain people.
| Can receive | Cannot receive | Special exception |
|---|---|---|
|
|
A DPIIT-recognised startup can grant options to promoters and 10%-plus directors for 10 years from incorporation (the period was 5 years until the 2019 amendment). |
Listed companies follow a different rulebook: SEBI’s Share Based Employee Benefits and Sweat Equity Regulations, 2021. This guide is about the far more common case: private limited companies and startups.
With eligibility settled, Ananya faced the part that scares most founders: the paperwork.
Chapter 4: Setting it up, step by step
A valid ESOP is built in a fixed order. Skip a step and your grants can be challenged later, usually at the worst moment: during an investor’s due diligence.
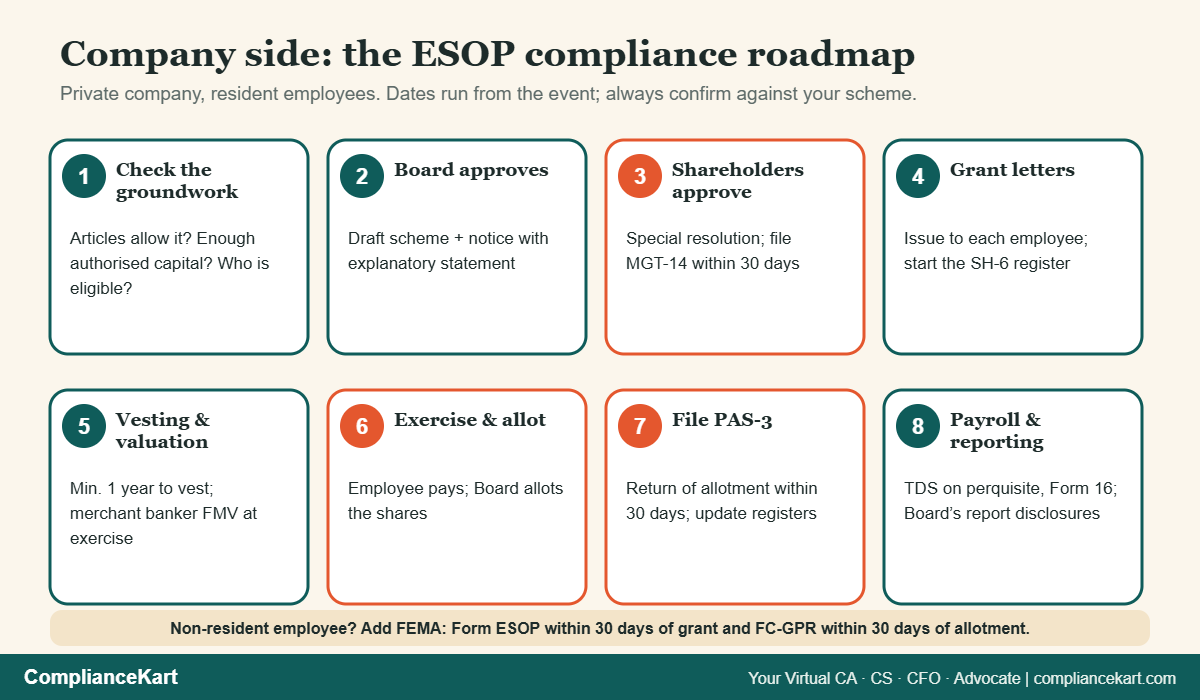
Step 1: Groundwork
Your Articles of Association must allow it, and your authorised share capital must be large enough to hold the pool. If not, increase it first.
Step 2: Board approves
The Board approves the draft ESOP scheme and the notice calling the shareholders’ meeting, with an explanatory statement.
Step 3: Shareholders pass a special resolution
The scheme needs a special resolution (75% of votes cast in favour). File Form MGT-14 with the Registrar of Companies within 30 days. The explanatory statement must tell shareholders, among other things: the total options, which employees qualify, the vesting conditions, the exercise price (or the formula), the exercise period, the maximum options per employee, and how options will be valued.
A separate special resolution is needed to grant options to employees of a subsidiary or holding company, or to identified employees who receive 1% or more of the issued capital in a year.
Step 4: Issue grant letters and open the register
Each employee gets a written grant. The company records it in the Register of Employee Stock Options (Form SH-6). Options cannot be transferred, pledged or mortgaged by the employee. And remember: no dividend or vote until shares are actually allotted.
Step 5: Exercise and allot
When the employee exercises and pays, the Board allots the shares. File Form PAS-3 (return of allotment) within 30 days, and update the registers.
Step 6: Payroll and annual disclosure
The perquisite goes into payroll, with TDS and Form 16 (we cover this in Chapter 8). ESOP details must also be disclosed in the Board’s report every year. If you later want to change the scheme’s terms, you need a fresh special resolution, and the change must not harm employees.
We can walk you through the resolutions, ROC filings, registers and payroll hand-offs in the right order. Share your cap table and hiring plan to begin.
Scheme approved, Ananya turned to the number that keeps founders awake: how many shares to set aside.
Related reading: Share capital, allotment and ESOPs (Company Law for Startups, Part 4) and how to issue shares in a private limited company.
Chapter 5: How big should the pool be?
No law fixes the pool size. It is negotiation and market practice. Early-stage startups often reserve something in the range of 5% to 15% of the company, but your hiring plan, not a rule of thumb, should decide it.
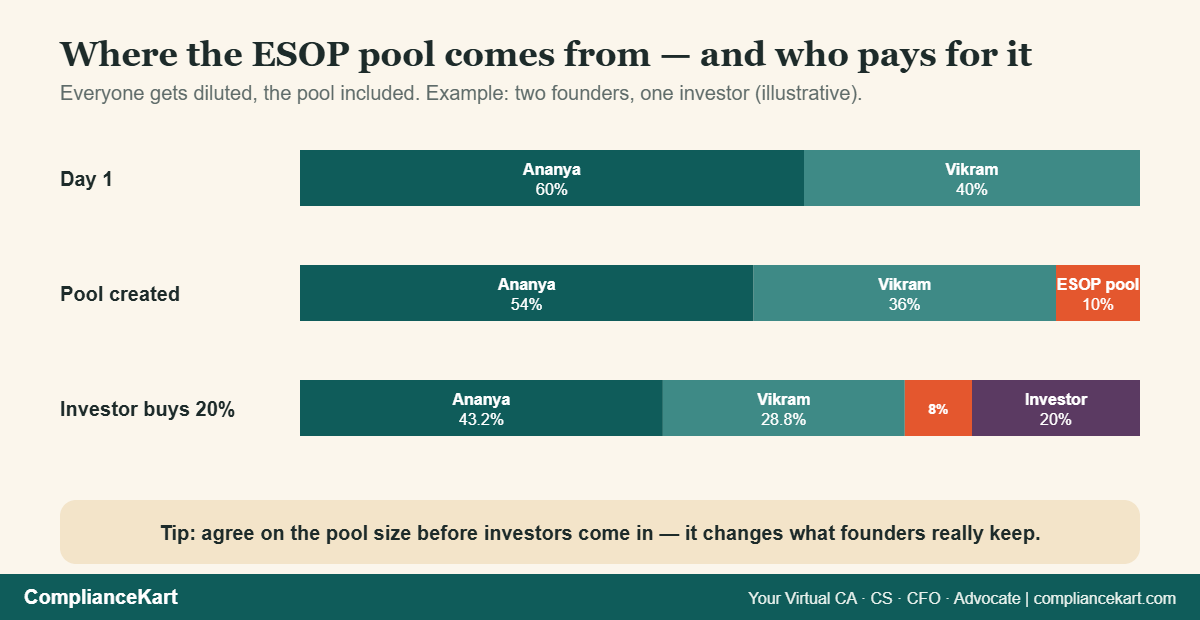
A simple way to size it: list the hires you plan over the next 18 to 24 months, note roughly what stake each role deserves, and add them up. Add a cushion for surprises.
Two truths founders learn late:
- Investors usually want the pool created before their money comes in. That means existing shareholders absorb the dilution. Read more on how this changes valuation in our guide to pre-money vs post-money valuation.
- An empty pool is an asset; a spent pool is a problem. Running out of options means the next hire gets cash you do not have.
Priya doesn’t care about the pool, though. She wants to know when her options actually become hers.
Chapter 6: Vesting, the waiting game
Vesting is how the company says: “Stay with us, and these become yours gradually.” The usual shape is four years with a one-year cliff.
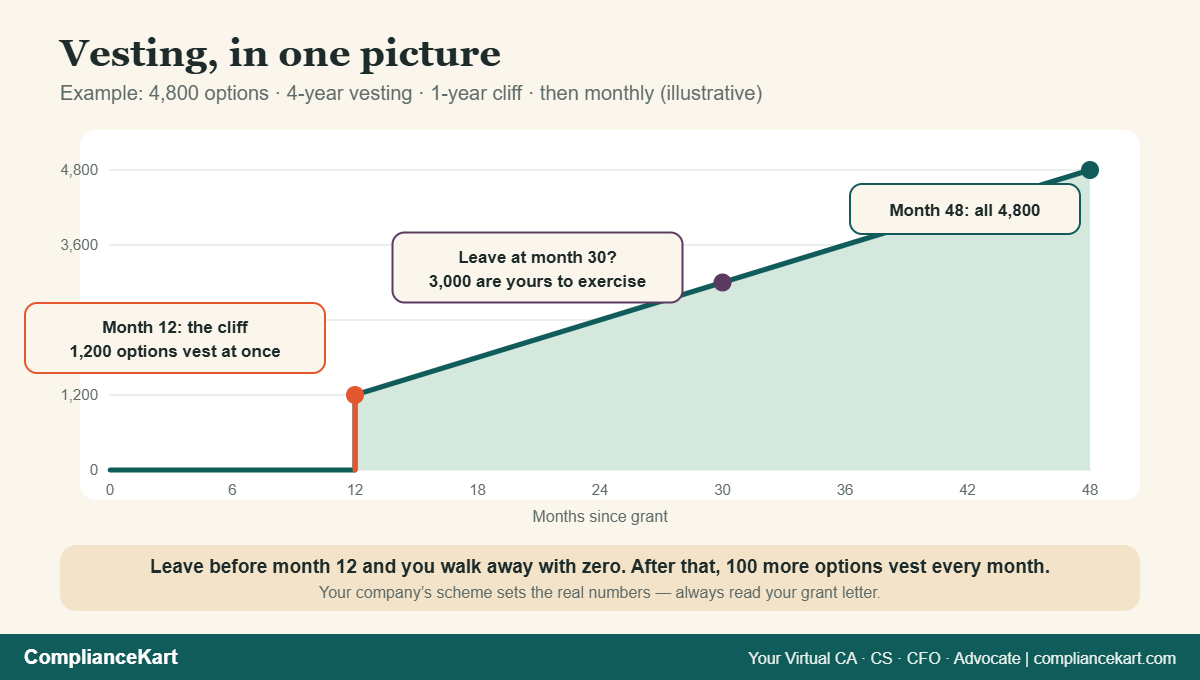
Priya’s grant: 4,800 options. At month 12, 1,200 vest together (the cliff). After that, 100 vest each month. Leave at month 10 and she gets nothing. Leave at month 30 and 3,000 are hers to exercise.
Leavers: what happens when someone quits?
The law leaves this to your scheme. Common terms (market practice, not law):
- Unvested options lapse when the employee leaves.
- Vested options must usually be exercised within a short window, often 30 to 90 days.
- Bad leaver (fired for misconduct, breach of contract): even vested options may lapse.
- Exit events (acquisition, IPO): the scheme may speed up vesting. This is not automatic; it must be written in.
All of this lives in one document. Here is what it looks like, with the lines to read twice.
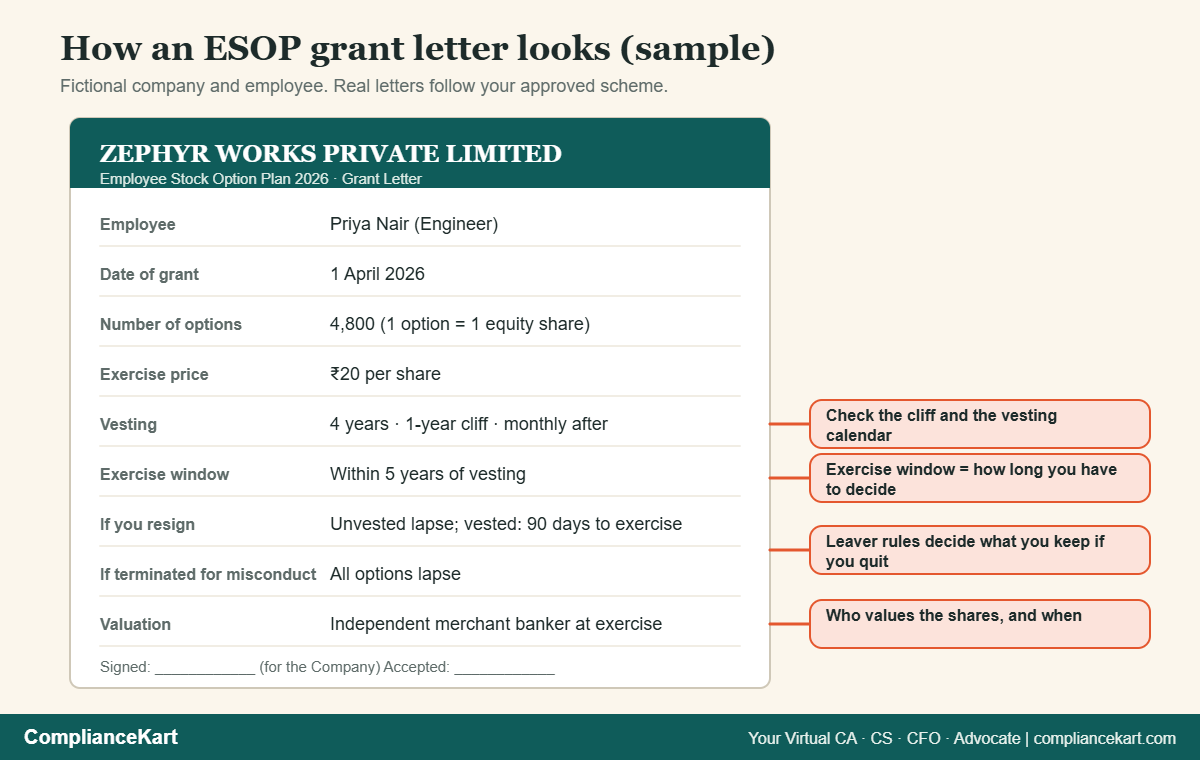
Priya read hers twice and found the one thing most employees miss: the exercise window. Miss it and the options simply expire. Which brings us to the number that decides everything: value.
Chapter 7: Price vs value, the number everyone argues about
Two numbers drive every ESOP. Do not mix them up.
| Exercise price | Fair market value (FMV) | |
|---|---|---|
| What it is | What the employee pays per share | What the share is worth on exercise day |
| Who sets it | The company, through the scheme (face value, a discount, or market price) | Determined by rule: exchange price if listed; a merchant banker if unlisted |
| Why it matters | Employee’s cash cost | Decides the taxable perquisite and the later cost of acquisition |
For unlisted shares (almost every startup), FMV must be certified by a SEBI-registered Category I merchant banker. The valuation date can be the exercise date, or an earlier date not more than 180 days before the exercise. A valuation report that is even one day too old can leave you with the wrong tax figure.
Three traps:
- The last funding round price is not automatically the FMV for tax.
- One report cannot be stretched across exercises ten months apart.
- The tax valuation (merchant banker) is different from the accounting expense of options, which the company records over the vesting period. Different purpose, different number.
Want to understand how valuations are built? See our explainer on startup valuation methods.
Two years passed. Zephyr raised money. The share was now worth ₹220. Priya’s accountant said just five words: “Now the tax chapter begins.”
Chapter 8: The tax chapter (read this twice)
8.1 Two bites, at two moments
| Moment | Taxed? | How |
|---|---|---|
| Grant | No | Nothing has been bought yet |
| Vesting | No | Still just a right |
| Exercise | Yes | FMV minus price paid is a salary perquisite. Employer deducts TDS |
| Holding the shares | No | Until you sell |
| Dividend received | Yes | Taxed as dividend income |
| Sale | Yes | Capital gains on sale price minus FMV taken at exercise |
Which law applies? The Income-tax Act, 2025 took effect on 1 April 2026. For ESOP exercises from that date, the perquisite is covered by section 17(1)(d) (earlier 17(2)(vi) of the 1961 Act) and the employer’s TDS by section 392 (earlier section 192). For exercises before 1 April 2026, the 1961 Act continues to apply.
8.2 Priya’s numbers
Priya has vested options. She exercises 1,000 of them in tax year 2028-29. Then she holds the shares for over two years and sells.
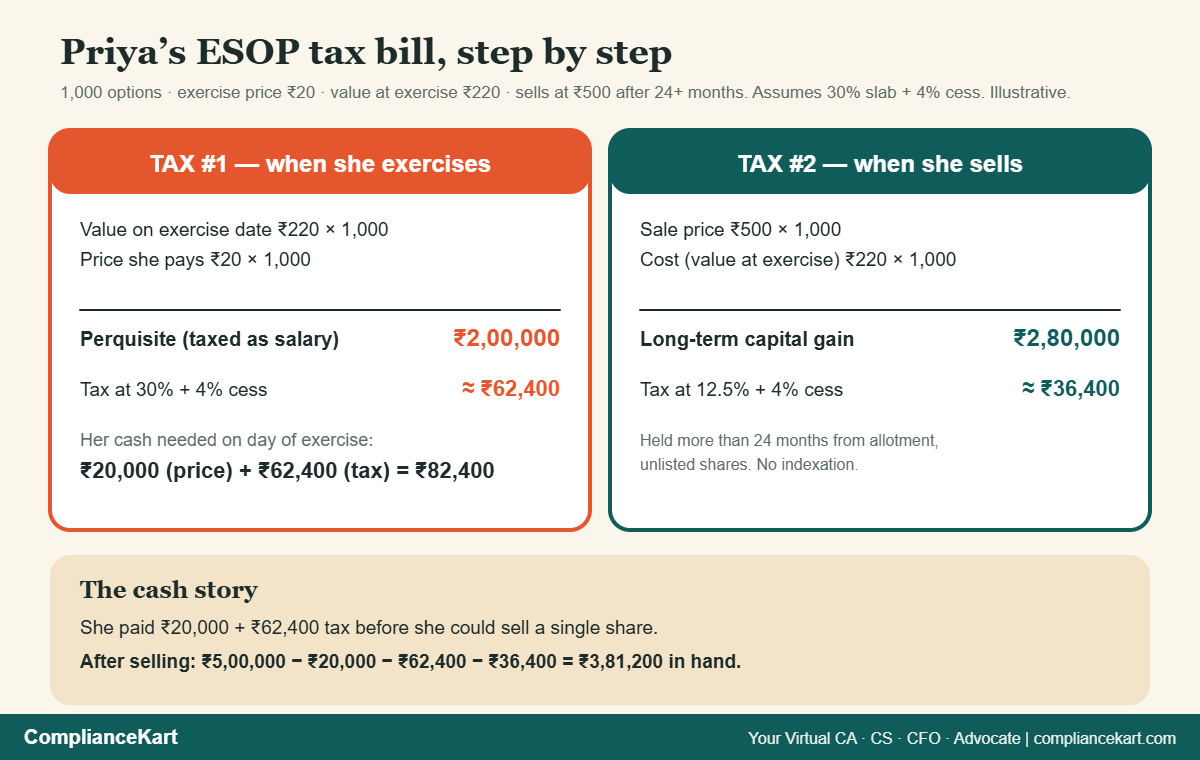
- At exercise: (₹220 − ₹20) × 1,000 = ₹2,00,000 added to her salary. At the top slab of 30% plus 4% cess, that is about ₹62,400. Her real slab may be lower.
- At sale: she sells at ₹500. Her cost is the ₹220 FMV taken at exercise, not the ₹20 she paid. Gain: (₹500 − ₹220) × 1,000 = ₹2,80,000. Long-term, unlisted: 12.5% plus cess = about ₹36,400.
8.3 Capital gains: what changes the rate
| Shares | Long-term if held | Long-term rate | Short-term rate |
|---|---|---|---|
| Unlisted (most startups) | More than 24 months | 12.5%, no indexation | At your slab rate |
| Listed equity (STT paid) | More than 12 months | 12.5% on gains above ₹1.25 lakh a year | 20% |
Add surcharge (if applicable) and 4% cess. The holding period runs from allotment (the exercise date), not from the grant date. Rates and thresholds are current for the 2026-27 tax year; confirm them whenever you sell.
8.4 The startup relief: tax deferral
If the employer is an eligible start-up, the employee need not pay the perquisite tax on exercise day. The idea: do not tax people on shares they cannot yet sell.
| Ordinary employer | Eligible start-up | |
|---|---|---|
| TDS on perquisite | At exercise | Deferred |
| Tax becomes payable | Immediately | Within 14 days of the earliest of: 60 months after the end of the tax year of allotment; sale of the shares; the employee leaving the employer |
| Who qualifies | Everyone | Only a company/LLP that is DPIIT-recognised and holds the Inter-Ministerial Board certificate (section 140 of the 2025 Act; earlier section 80-IAC) |
Three things to remember. (1) DPIIT recognition alone is not enough; many startups hold it but not the Board certificate. (2) It is a deferral, not a waiver: the taxable value is still fixed at exercise, so if the shares later fall, the tax figure does not. (3) For shares allotted before 1 April 2026 the earlier law’s shorter window (48 months) applied; confirm which applies to your allotment.
8.5 The company’s side of the tax story
- TDS and Form 16: the employer must withhold on the perquisite (unless deferral applies) and report it in Form 16 and Form 12BA.
- Deduction for the company: the Karnataka High Court, in CIT v. Biocon Ltd. ((2021) 430 ITR 151), upheld the Bangalore Special Bench view that the ESOP discount is deductible as business expenditure under section 37(1), spread over the vesting period. Facts matter, so keep the scheme, valuation and accounting trail clean.
8.6 Smart planning ideas (not advice)
- Know the cash: price plus tax, ready on exercise day.
- Watch the valuation calendar: the share’s FMV often jumps after a funding round. If your window allows, exercising before a re-rating can mean a smaller perquisite (but only if you can afford the cost and risk).
- Don’t exercise everything in one year unless you must: spreading may keep income in lower slabs.
- Hold past 24 months after exercise for the long-term rate on unlisted shares.
- Leaving the job? Decide before the exercise window closes.
- Company: confirm eligible-start-up status before promising deferral; keep the valuation report under 180 days old; set up payroll to handle the perquisite.
- Keep paper: grant letter, exercise notice, valuation report, Form 12BA, sale contract. They are your proof at filing time. See our note on income tax return filing.
Tell us your grant, vesting and expected exercise date. We will help you map the tax, the cash needed and the filing trail.
If you also hold RSUs from a global parent, read ESOPs and RSUs for Hyderabad tech employees.
Priya paid, held, and thanked her accountant. But one afternoon a new hire from Dubai asked: “Can I get options too?”
Chapter 9: When the world is bigger than India (FEMA)
Employees outside India, or an employer parent abroad, bring the Foreign Exchange Management Act (FEMA) into play.
- Indian company, non-resident employee or director: allowed under the automatic route, subject to the sector’s foreign-investment conditions. The company reports the grant on Form ESOP within 30 days and the allotment on Form FC-GPR within 30 days, through the RBI’s FIRMS portal.
- Foreign parent, Indian-resident employee (ESOP/RSU of the parent): separate overseas-investment rules apply, plus tax disclosures in the Indian return (Schedule FA) and foreign tax credit questions.
Our guides on foreign investment under FEMA and FEMA compliance go deeper. Next, Ananya asked whether ESOP was even the right tool.
Chapter 10: ESOP vs the alternatives
| Tool | How it works | Employee pays? | Tax moment | Best when |
|---|---|---|---|---|
| ESOP | Right to buy shares at a fixed price | Yes, the exercise price | Exercise (perquisite), then sale (capital gains) | You want long-term retention |
| RSU | Shares are given on vesting, no price | No | When shares are allotted (perquisite), then sale | Employees cannot fund an exercise price |
| Sweat equity | Shares issued for know-how or value added (Section 54) | Usually a discount | Perquisite on allotment, then sale | Rewarding specific contribution; separate rules apply |
| SAR / phantom stock | Cash payout linked to share value, no shares | No | Salary when paid | You want rewards without dilution or share-issue formalities |
| ESPS | Employees buy shares directly, often at a discount | Yes | Perquisite on the discount, then sale | Wider, simpler share ownership |
No tool is “best”. The right one depends on cash, hiring stage, and how much dilution you can accept. Ananya stayed with ESOPs. Then she made her list of everything that could go wrong.
Chapter 11: Where ESOPs go wrong
The 14 costly mistakes
| # | Mistake | What it costs you | The fix |
|---|---|---|---|
| 1 | Verbal promises (“you’ll get 1%”) | Disputes, lost trust | Written grant letter for every promise |
| 2 | Granting before shareholder approval | Grants can be challenged | Follow the Chapter 4 order |
| 3 | Pool too small or spent early | Cannot hire or reward | Size it from a 24-month hiring plan |
| 4 | Valuation older than 180 days | Wrong perquisite and TDS | Calendar the valuation date |
| 5 | Forgetting TDS at exercise | Employer liability, interest | Payroll checklist per exercise |
| 6 | Missing MGT-14, PAS-3, SH-6, Board report | Defaults found in due diligence | Compliance calendar |
| 7 | Options to promoters or 10%+ directors without the startup exception | Invalid grant | Check eligibility first |
| 8 | Ignoring the tax cash gap | Employee cannot afford to exercise | Plan liquidity or deferral |
| 9 | Vague leaver rules | Ugly exits, litigation | Define good and bad leaver clearly |
| 10 | Scheme “in a drawer”, never explained | Options feel worthless; no retention value | Run a team briefing |
| 11 | Copy-pasting a foreign (US-style) template | Clauses that clash with Indian law | Use an India-built scheme |
| 12 | Assuming deferral because you are DPIIT-recognised | Surprise tax bill | Check the Board certificate |
| 13 | Non-resident grants without FEMA reporting | Compounding and penalties | File Form ESOP and FC-GPR on time |
| 14 | Messy cap table spreadsheets | Delayed funding rounds | Keep one reconciled cap table |
Bottlenecks: where plans get stuck
- No liquidity. Private shares cannot be sold on an exchange. Value turns into cash only through a sale to an investor, an acquisition, an IPO, or a company buyback. (Tax treatment of buybacks has changed in recent years, so confirm before relying on one.)
- Tax before cash. See Chapter 8: the perquisite is taxed even though nothing was sold.
- Valuation disputes between founders, investors and employees.
- Investor conditions: a bigger pool, different vesting, or founder re-vesting in a funding round. See fundraising, term sheet and SHA.
- Exit events: what happens to unvested options in an acquisition must be written in advance.
Chapter 12: Your checklists
Founder’s checklist
- Articles allow ESOP; authorised capital is enough.
- Pool size backed by a hiring plan.
- Draft scheme: eligibility, vesting, exercise price, leaver rules, exit rules.
- Board approval, then special resolution; MGT-14 filed.
- Grant letters signed; SH-6 register started.
- Merchant banker relationship ready for exercise-date FMV.
- Payroll briefed on perquisite and TDS.
- Eligible-start-up status confirmed (if you want deferral).
- PAS-3 filed within 30 days of each allotment.
- Annual Board’s report disclosure done.
Employee’s 10 questions before you sign
- How many options, as a percentage of the company?
- What is the exercise price, and who decides it?
- What is the vesting schedule and cliff?
- How long is the exercise window after I leave?
- What happens if I am terminated?
- What happens if the company is acquired?
- Is the company an eligible start-up for tax deferral?
- Who values the shares, and how often?
- Are there any buy-back or transfer restrictions?
- Can I see the full scheme document and the latest cap table summary?
Chapter 13: Explain it to your team
An ESOP nobody understands retains nobody. Show employees what their statement will look like, and brief them with a short deck.
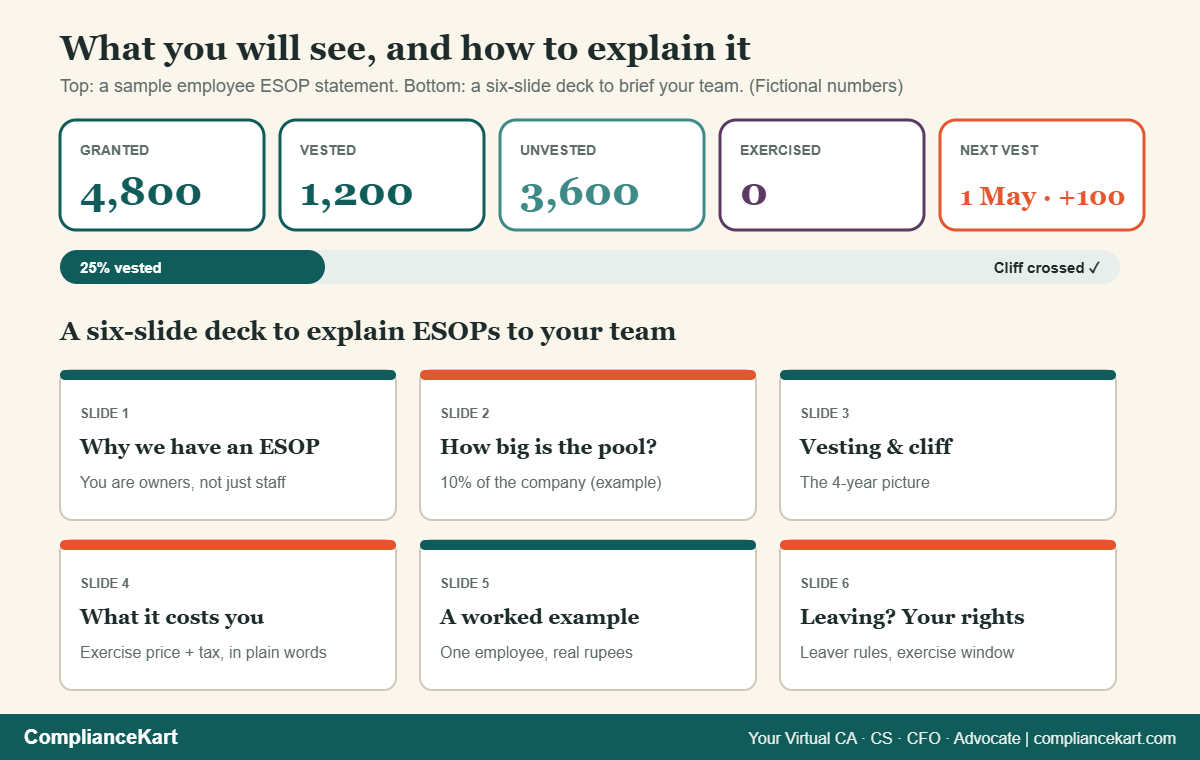
Six slides are enough: why we have an ESOP, pool size, vesting, what it costs the employee, one worked example, and leaver rights.
Chapter 14: The Hyderabad angle
Founders around Hitech City, Kondapur, Gachibowli, Kokapet and Financial District compete for engineers with large global employers. Cash alone rarely wins. A clear, well-explained ESOP often does. Hyderabad employees also frequently hold RSUs or options of a foreign parent, which is why the tax and FEMA chapters above matter locally.
Epilogue: what Priya did
Priya declined the Gachibowli offer. Her reason was not a promise on paper. It was that she understood the paper: how it vested, what it cost, what the taxman would take, and what she would keep.
That is the whole point of this guide. An ESOP is only as valuable as the understanding behind it.
Why work with ComplianceKart
ESOPs touch company law, tax, payroll, foreign exchange and contracts, all at once. Most problems appear in the gaps between them.
ComplianceKart is a boutique practice bringing Chartered Accountants, Company Secretaries and advocates under one roof. Think of a multi-speciality hospital: you do not run between separate clinics for the heart, the bones and the blood tests. One team looks at the whole patient, and each specialist knows what the others found. Your ESOP gets the same treatment.
How we can help (scope depends on your case):
- Scheme and approvals: drafting inputs, Board and shareholder resolutions, MGT-14.
- ROC and registers: PAS-3, SH-6, Board’s report inputs. See our ROC annual compliance and startup compliance services.
- Tax planning: perquisite and capital-gains mapping, TDS and Form 16 coordination, return filing.
- FEMA: Form ESOP and FC-GPR for non-resident employees.
- Agreements and due-diligence readiness with the Virtual CFO, CS and Advocate team.
- Valuation: we coordinate with the merchant banker your exercise-date valuation needs.
Share your scheme, cap table or grant letter. We will tell you what is in order and what needs fixing. No obligation.
Contact: compliancekart.com · team@compliancekart.com · +91 99595 36391 · 7th Floor, Pranava Business Park, Innov8, Kondapur, Hitech City Road, Hyderabad 500084.
FAQs
Is ESOP income taxable if I have not sold the shares?
Yes. The perquisite (FMV minus price paid) is taxed as salary at exercise, even though you have received no cash. Employees of eligible start-ups may defer the payment (Chapter 8.4).
Can a private company offer ESOPs?
Yes, under Section 62(1)(b) and Rule 12, with a special resolution of shareholders, an explanatory statement and the filings described in Chapter 4.
Is a vesting period compulsory?
Yes. There must be at least one year between grant and vesting. Your scheme can set a longer schedule.
Can founders get ESOPs?
Promoters and directors holding more than 10% generally cannot, unless the company is a DPIIT-recognised startup, in which case the restriction is lifted for 10 years from incorporation.
What happens to my ESOPs if I resign?
It depends on your scheme. Typically unvested options lapse and vested options must be exercised within a stated window. Read the leaver clause before you sign.
Do I need a valuation to exercise?
For unlisted shares, yes. A SEBI-registered Category I merchant banker must certify FMV as of the exercise date or a date up to 180 days earlier, to compute the perquisite.
Sources and further reading
- Companies Act, 2013, Sections 2(37) and 62(1)(b); Rule 12, Companies (Share Capital and Debentures) Rules, 2014 (as amended in 2016 and 2019), text at ca2013.com.
- Income Tax Department: Taxation of employee stock option plan; Fair market value rules; Income-tax Act, 2025; Section 140; Taxation of start-ups.
- Income-tax Act, 2025, Sections 17(1)(d), 289(3) and 392(3) (text of section 289 at Indian Kanoon).
- Biocon Ltd. v. DCIT (Special Bench, ITAT Bangalore, 2013) 144 ITD 21, affirmed in CIT v. Biocon Ltd. (2021) 430 ITR 151 (Karnataka).
- Reserve Bank of India: ESOP and sweat equity shares to persons resident outside India; Non-debt Instruments Rules, 2019.
Need this done for your business?
Send us one message. A CA, CS or Advocate replies within a working day — no forms, no obligation.