How to Convert an LLP into a Private Limited Company: Procedure, Tax and Compliance Implications
Converting an LLP to a private limited company in Hyderabad? Procedure under section 366, tax points and post-conversion compliance for founders in Kondapur and Hitech City.
A Kondapur software LLP has an investor ready to put in money, but the investor wants shares, a board and a structure that supports employee stock options. That is a common trigger to convert the LLP into a private limited company.
Short answer: an LLP can register as a company under section 366 of the Companies Act, 2013, read with the Companies (Authorised to Register) Rules, 2014, by filing Form URC-1 along with the incorporation forms. The tax side needs separate planning, because the Income-tax law gives a specific exemption for converting a company into an LLP, but not an equally clear one for the reverse.
Why founders convert
- Investors usually invest in shares of a company, not LLP contributions.
- Employee stock option plans are available to companies.
- A company structure is often expected by large clients and lenders.
If you are still weighing the two structures, read why founders prefer a private limited company over an LLP.
Procedure at a glance
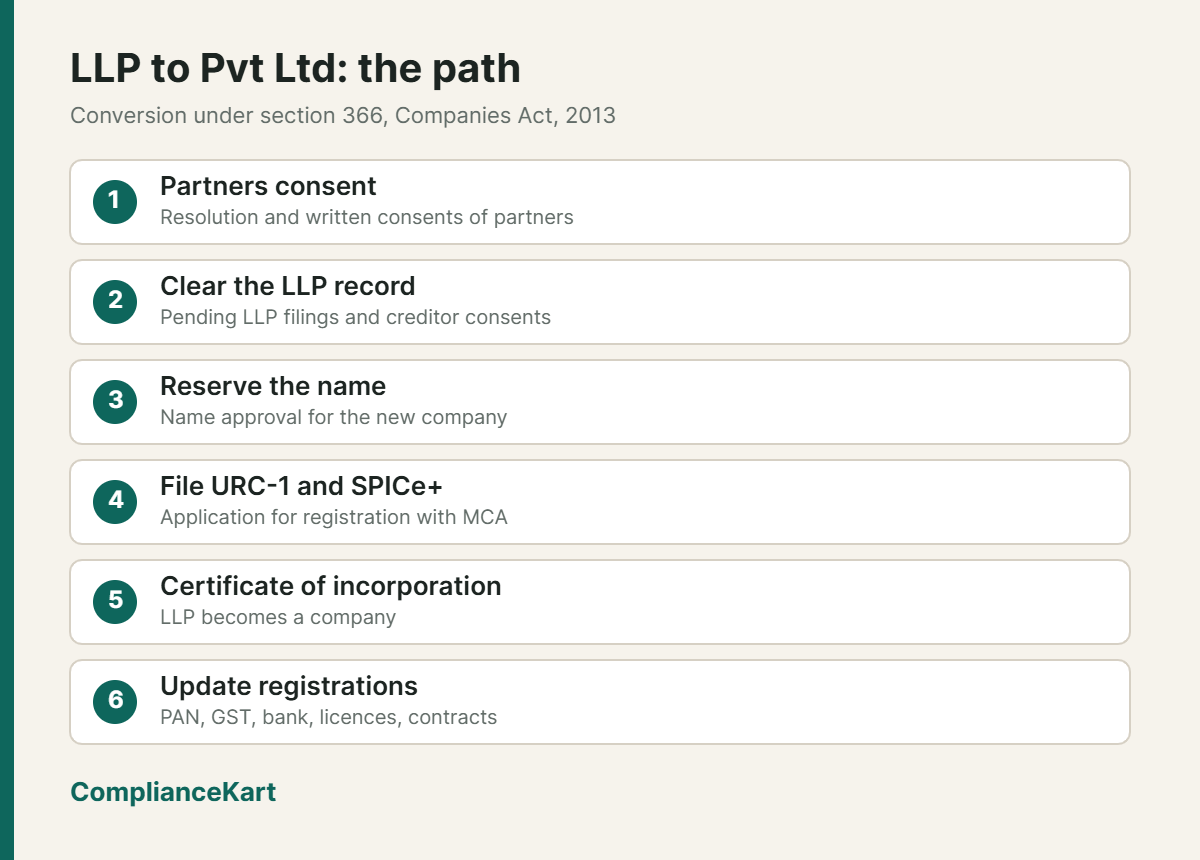
The partners become the company’s shareholders, and the LLP’s assets and liabilities vest in the company on registration. Pending LLP filings should be completed first, and consent of secured creditors is normally needed.
Need help with this? Speak to the ComplianceKart team: call 9959536391 or WhatsApp us.
Tax implications
This is where most of the planning goes.
- Capital gains. Section 47(xiiib) of the Income-tax Act, 1961 exempts the conversion of a company into an LLP, subject to conditions. There is no equivalent express exemption for converting an LLP into a company. Whether the exemption for a firm succeeded by a company, in section 47(xiii), extends to an LLP is a debated question, so the tax position should be examined before converting.
- New tax law. The Income-tax Act, 2025 applies from tax year 2026-27, so the provisions applicable on the conversion date need to be checked under that Act.
- Tax rate. An LLP is taxed at 30 per cent plus applicable surcharge and cess. A domestic company can choose the 22 per cent concessional regime if it meets the conditions.
- Losses and credits. Whether the LLP’s carried-forward losses and unutilised credits move to the company needs specific review.
- Stamp duty and GST. State stamp duty on vesting of property, and GST registration and input tax credit transfer, should be reviewed for Telangana.
Compliance after conversion
| Area | What changes |
|---|---|
| Company law | Board meetings, AGM, statutory registers, AOC-4 and MGT-7 every year, auditor appointment |
| Registrations | Update PAN records, GST, bank accounts, Shops and Establishment and other licences |
| Contracts | Inform clients, vendors and lenders; review contracts that need consent |
| Payroll | Employer registrations for PF and ESI move to the company |
For the yearly calendar after conversion, see our annual compliance calendar for Hyderabad founders.
Common mistakes
- Converting before checking the capital gains position.
- Leaving LLP filings pending, which can delay the application.
- Forgetting to update GST and bank records, causing payment and credit issues.
Why work with ComplianceKart
ComplianceKart is a boutique practice bringing Chartered Accountants, Company Secretaries and advocates under one roof. Company law, tax and regulatory filings overlap, and a gap in one shows up as a problem in another. Think of a multi-speciality hospital: the right specialists look at your case together, so you are not running between clinics. We work with founders and businesses across Hyderabad, including Hitech City, Gachibowli and Kondapur.
Frequently asked questions
Can an LLP be converted into a private limited company?
Yes. An LLP can register as a company under section 366 of the Companies Act, 2013 through Form URC-1 and the incorporation forms.
Is the conversion tax-free?
Not automatically. There is no express exemption for LLP-to-company conversion, so the capital gains position needs advice before converting.
Do the partners become shareholders?
Yes, the partners become shareholders of the new company.
Does the GST number change?
The company is a new legal person for many registrations, so GST and other registrations must be updated or obtained.
Will contracts continue?
Assets and liabilities vest in the company, but contracts that need consent should be reviewed with the other party.
General information as of October 2026, not legal or tax advice.
Need this done for your business?
Send us one message. A CA, CS or Advocate replies within a working day — no forms, no obligation.