Buying a Flat in Hyderabad? Here’s Exactly When GST Applies — and When It Doesn’t
GST on flats, commercial units, land, rent and JDAs explained — 1% and 5% rates, ITC rules and when no GST applies. A guide for Hyderabad buyers and builders.
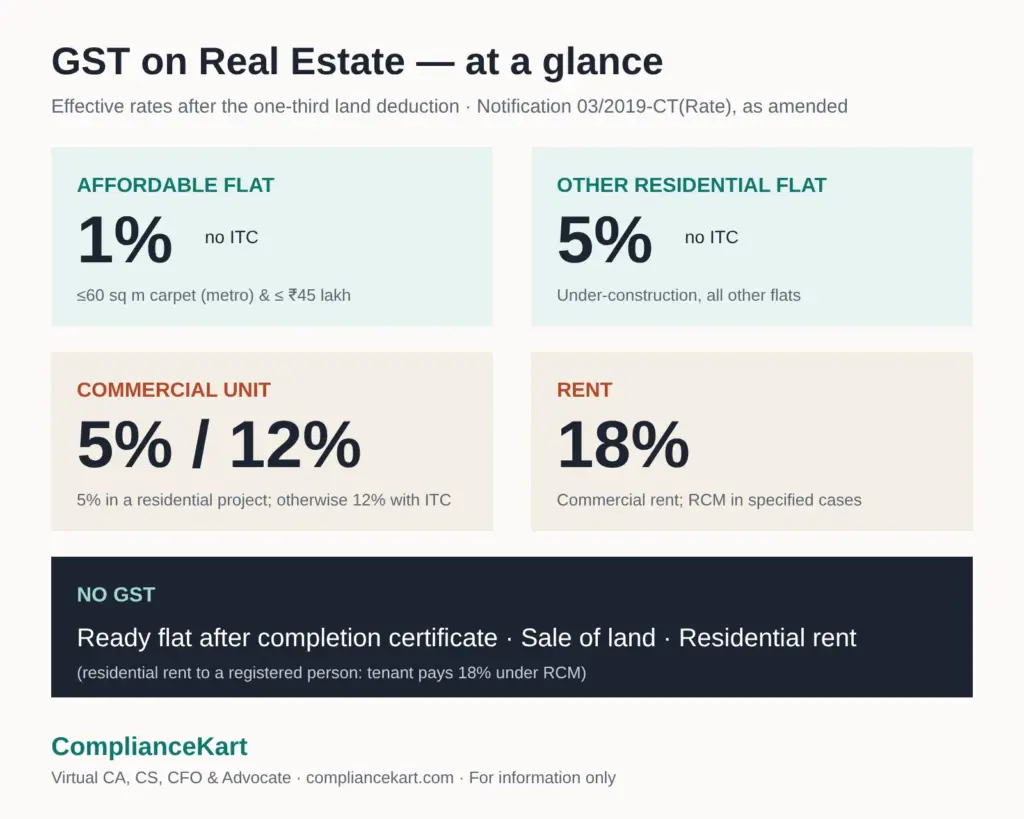
You have shortlisted a 2BHK in Kokapet, and the builder’s cost sheet shows a “GST” line. A friend bought a ready flat in Kondapur and paid none. Both are correct.
This guide explains the rates, the affordable-housing test, the ITC block for builders, GST on rent and the common mistakes we see.
Which law governs GST on real estate?
Construction of a building intended for sale is a supply of service when any consideration is received before the completion certificate (Schedule II, para 5(b), CGST Act, 2017). Sale of land and sale of a building after completion are neither goods nor services (Schedule III, para 5). The rates for residential real estate projects (RREPs) come from Notification No. 03/2019–Central Tax (Rate), effective 1 April 2019.
GST rates on real estate
| Transaction | Effective GST | ITC available? |
|---|---|---|
| Affordable residential flat (under construction) | 1% | No |
| Other residential flat (under construction) | 5% | No |
| Commercial unit in an RREP (commercial ≤15% of carpet area) | 5% | No |
| Commercial property outside an RREP | 12% (18% less one-third land deduction) | Yes |
| Ready property with completion certificate | Nil | — |
| Land sale | Nil | — |
| Commercial rent | 18% | Yes, for the tenant (subject to Section 16) |
The notified rate is charged on the full agreement value; a one-third deduction for land brings the effective rate down (e.g. 7.5% × ⅔ = 5%).
Does my flat qualify as “affordable housing”?
A flat is affordable if both tests are met:
- Carpet area: up to 60 sq m in metro cities (Hyderabad is notified as a metro) or 90 sq m elsewhere.
- Value: gross amount up to ₹45 lakh.
Example: A 58 sq m flat in Narsingi priced at ₹52 lakh fails the value test, so GST is 5%, i.e. about ₹2.6 lakh, not ₹52,000.
Why builders cannot claim ITC — and the 80% rule
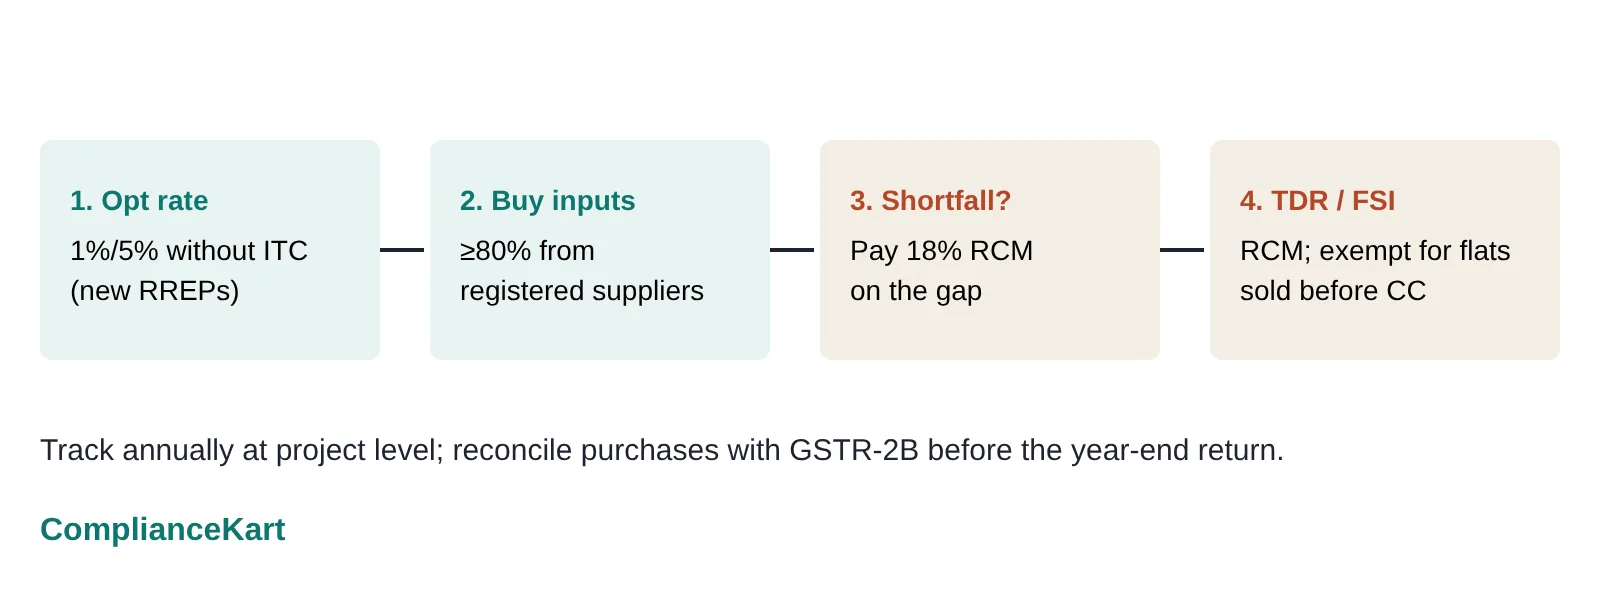
At the concessional 1%/5% rates, promoters cannot take ITC. To prevent leakage, at least 80% of inputs and input services (by value) must be bought from registered persons; any shortfall is taxed under reverse charge at 18% (cement purchased from unregistered suppliers is taxed at its applicable rate, now 18% after the September 2025 rate changes).
For businesses building their own premises, Section 17(5)(c) and (d) block ITC on construction of immovable property. The Supreme Court in Chief Commissioner of CGST v. Safari Retreats (3 October 2024) applied a functionality test for “plant”, but the Finance Act, 2025 amended Section 17(5)(d) retrospectively. Treat ITC on buildings as litigative and take advice before claiming.
GST on renting property
- Residential rent for use as a residence by an individual: exempt. Where the tenant is GST-registered, the tenant pays 18% under reverse charge (from 18 July 2022).
- Commercial rent by a registered landlord: 18% forward charge.
- Unregistered landlord → registered tenant (commercial): tenant pays 18% under RCM (from 10 October 2024), except where the tenant is a composition taxpayer (from 16 January 2025).
Common mistakes
- Paying GST on a flat bought after the completion certificate was issued.
- Assuming every flat under ₹45 lakh is affordable without checking carpet area.
- Builders ignoring the 80% registered-purchase test until the annual return.
- Landlords in Hitech City and Gachibowli missing RCM on commercial leases.
- Overlooking GST on development rights in joint development agreements.
Real estate GST in Hyderabad
Western Hyderabad — Kokapet, Narsingi, the Financial District and Gachibowli — has large under-construction inventory, so buyers there most often face the 1% vs 5% question. Office and retail leasing around Hitech City and Kondapur makes commercial-rent RCM a recurring compliance item for tenants.
Why work with ComplianceKart
Real estate GST touches tax, contracts and sometimes litigation at once. ComplianceKart is a boutique practice bringing CAs, CSs and advocates under one roof. Think of it like a multi-speciality hospital: the tax specialist, the documentation specialist and the litigation specialist look at the same file together, so nothing falls between departments. We help builders with project-level GST compliance and RCM tracking, and help buyers and landlords understand what they owe.
WhatsApp us Email team@compliancekart.com Call 99595 36391
FAQs
Is GST payable on a resale flat?
No. A resale of a completed flat is a sale of immovable property and is outside GST; stamp duty applies.
Is GST charged on the land value of a flat?
The rate is applied to the full price, but a deemed one-third land deduction is built into the effective 1%/5% rates.
Can a homebuyer claim ITC on GST paid?
No. Builders cannot claim ITC at 1%/5%, and an individual buyer has no output tax to set it off against.
Does GST apply on parking or club membership?
If charged as part of the flat agreement before completion, it follows the flat’s rate; separately charged services are taxed at their own applicable rate, so check how your agreement splits them.
Is GST payable on maintenance charges?
RWA charges up to ₹7,500 per member per month are exempt; above that, 18% applies on the full amount, subject to the RWA’s turnover threshold.
Related guides
- Buying a flat in Hyderabad: TDS, stamp duty and tax
- GST 2.0 rate changes and their impact on Hyderabad businesses
- GST registration in Hyderabad
- Received a GST notice? What to do next
Sources
CGST Act, 2017 — Schedules II & III, Section 17(5) (cbic-gst.gov.in) · Notification 03/2019-CT(Rate) · Notification 05/2022-CT(Rate) (residential rent RCM) · Notification 09/2024-CT(Rate) (commercial rent RCM) · Supreme Court, Safari Retreats, 3 Oct 2024 · Finance Act, 2025.
Takeaway: Check two things before paying GST on property — whether a completion certificate exists, and whether the flat meets both affordable-housing tests.
Need this done for your business?
Send us one message. A CA, CS or Advocate replies within a working day — no forms, no obligation.